Key takeaways
- Know where your money is. Regular cash forecasting helps you spot potential shortfalls before they become a problem.
- Keep your working capital moving. Managing payment terms and invoice cycles can help you meet day-to-day costs.
- Don't let surplus cash sit idle. Even a small difference in interest rates can make a big difference when you're holding £100,000 or more.
- Make the most of your banking relationship. A relationship manager who understands your business can help you think about how to manage your money more effectively.
What is liquidity management?
Liquidity management is the process of making sure your business has enough accessible money to cover its financial commitments, while making the most of any cash it doesn't need straight away.
It's important for businesses of all sizes, but it becomes increasingly valuable as your business grows.
You might have plans to expand, invest in equipment, or take on new premises. But you still need enough money available to pay your team, suppliers and everyday bills.
If you're planning your next stage of growth, it's also worth exploring how growth finance could support your plans.
The three pillars of effective liquidity management
If you’re an established business without treasury teams, you need to manage cash with more intention than an early-stage business.
Managing your liquidity well comes down to three things: knowing where your money is, keeping your working capital under control and making surplus cash work harder.
1. Cash visibility: knowing your position
Do you know exactly how much cash your business has available today?
If you're managing money across several accounts, it's easy to lose sight of the bigger picture. Having a clear view of your cash position helps you make better decisions about what you can afford to spend, save or invest.
Cash forecasting is a good place to start. Instead of relying on last month's bank statement, look ahead over the next four to twelve weeks. Map out the money you expect to receive and the payments you'll need to make. This can help you spot potential gaps early and plan around them.
Some businesses are unsure how many accounts to hold, and how to structure them. Find out more in our article on how many business bank accounts you really need.
For more practical tips, take a look at our guide on how to improve your business cashflow.
2. Working capital control: managing the day-to-day cycle
Your business might be profitable on paper, but that doesn't always mean you've got enough money available when you need it. Working capital, the money a business has available to fund its day-to-day operations and pay short-term bills, is affected by timing.
If customers take 60 days to settle invoices but suppliers expect payment within 30, you could find yourself short of cash. Seasonal businesses can face similar challenges when income fluctuates but regular costs stay the same.
Managing your working capital means keeping a close eye on these gaps and planning for your funding requirements.
One option is a business overdraft, which can provide a useful buffer when you need to cover short-term costs. You can use our overdraft cost calculator to understand potential borrowing costs.
Not sure which borrowing option suits your business? Read our guide comparing revolving credit facilities and overdrafts. If you’re a property-backed business with short-term cash needs, bridging finance could offer a solution.
3. Surplus cash optimisation: making idle money work
Once you've got a clear view of your cash position and day-to-day costs, there's another question worth asking: could your spare cash be working harder?
Many established businesses hold cash reserves for future investment, unexpected costs or simply peace of mind. But leaving that money in a current account earning little or no interest could mean missing out on an extra boost.
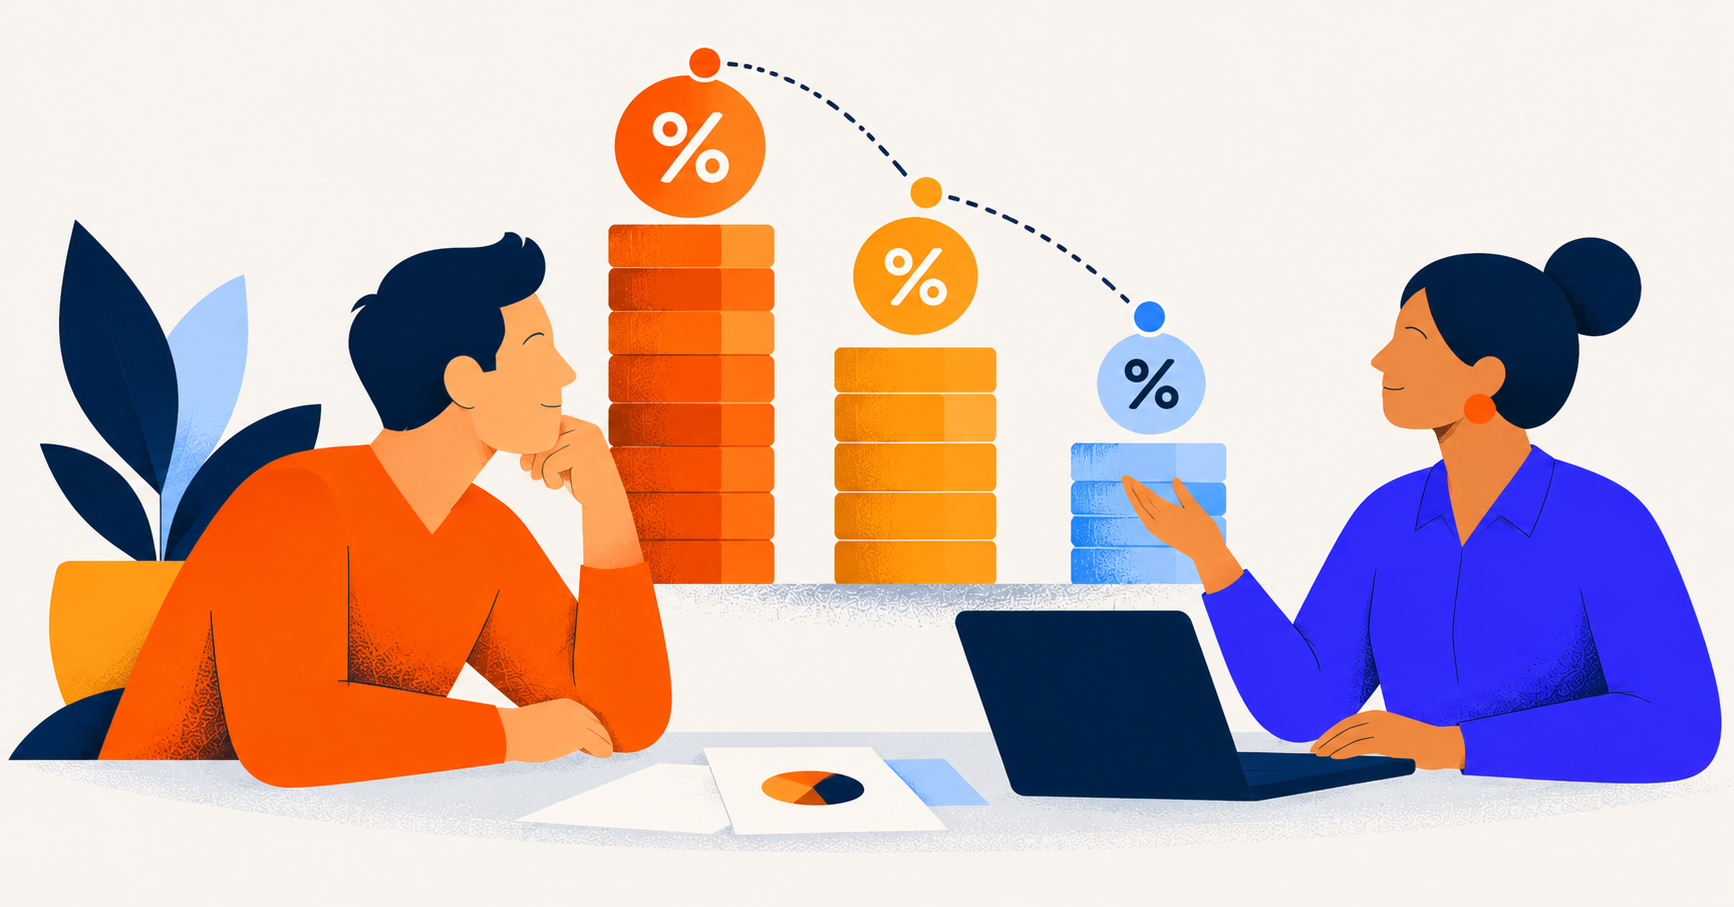
For example, if your business holds £250,000 in surplus cash, a difference of just 2% in annual interest could mean an extra £5,000 over a year, assuming the balance stays the same and before tax. That's money your business could put towards its next investment.
The key is finding the right balance between earning interest and keeping your money accessible. Explore Allica Bank's business savings accounts to see what options are available.
Comparing your options for surplus cash
Not all business savings accounts work in the same way. The right choice depends on when you'll need your money and how much flexibility you want.
Here are some options to consider:
- Easy access savings accounts: Useful when you want to earn interest while keeping your money accessible.
- Savings pots: Helps you separate money for different business needs while keeping track of your savings.
- Notice accounts: Often offering different interest rates in return for giving notice before withdrawing. Common notice periods include 95 and 180 days.
- Fixed-term deposits: Put money aside for a set period, such as six, 12 or 24 months, in return for an agreed interest rate.
Good financial planning means matching your savings choices to your business's cash needs. For example, money earmarked for next month's payroll should stay accessible. Cash you won't need for another year could be better suited to a longer-term account.
Our guide to choosing between notice and instant-access savings can help you weigh up your options.
Liquidity ratios: knowing where you stand
Two useful ways to check your business’s financial position are the current ratio and quick ratio.
Current ratio: This compares your current assets with your current liabilities. A ratio above 1.5 is generally considered healthy for many established businesses, although this varies by industry.
Quick ratio: This is similar, but excludes stock and other less liquid assets. It gives you a clearer picture of your ability to cover short-term commitments using assets you can turn into cash quickly.
Looking at these figures regularly can help you spot changes in your liquidity position.
For more on understanding your business finances, read our guide to the debt-to-equity ratio.
If you’d like to find out more about capital structure decisions, read our article on debt financing vs equity financing.
How your banking partner can support your liquidity strategy
Managing your money doesn't have to be something you figure out alone. A banking partner who understands your business can help.
Having someone who really understands your business, from your busy periods to your plans for growth, can make all the difference. You can discuss your cashflow, where to keep your spare cash, and whether your money could be working harder for your business.
At Allica Bank, we believe established businesses deserve more than just a bank account. That's why we combine smart banking tools with real people who understand business.
With a dedicated relationship manager, you've got someone to talk to about your business banking needs and plans for the future. And with our Business Rewards Account and linked Savings Pot, you can keep your day-to-day banking and savings connected.
Ready to make more of your business money?
Explore Allica's Business Rewards Account and see how smarter banking could help your business.
Frequently asked questions about liquidity management
What is liquidity management in simple terms?
Liquidity management means making sure your business has enough money available to pay its bills, while making the most of any spare cash.
It matters for every business, but becomes increasingly important as your business grows and your financial commitments increase.
What is the difference between liquidity management and cashflow management?
Cashflow management focuses on when money enters and leaves your business.
Liquidity management looks at the bigger picture, including how much cash you need to keep accessible, how you manage financial risks and what you do with surplus money.
What is liquidity risk for an established business?
Liquidity risk is the possibility that your business won't have enough accessible money to meet a payment when it's due.
Even profitable businesses can face liquidity problems if customers pay late or unexpected costs arise.
How much cash should a business hold in reserve?
There’s no one-size-fits-all answer, but a common starting point is enough cash to cover three months of operating costs. The right amount depends on your business's regular expenses, how predictable your income is and the industry you operate in.
What does liquidity governance mean for a business?
Liquidity governance simply means having clear rules about how your business manages its money. That includes deciding who can move money between accounts, how much cash to keep accessible and when surplus money can be saved or invested.
Having these rules in place can help your business make more consistent financial decisions.
Links were live and information was correct at the time of writing the article.
Disclaimer: This is information – not financial advice or recommendation.
The content and materials featured in this article are for information and education only, and are not intended to take into consideration any particular recipient’s financial situation. The product details referred to are correct at the time of writing. The information does not constitute financial advice or recommendation and should not be considered as such.